In mid-2017, ING Economic Bureau published an international study on the rise of electric cars. Main outcomes; barriers to electric cars will be broken within a few years and the European passenger car market is expected to be 100% electric by 2035. However, that transition also represents a huge challenge for the European car industry. Where does Europe stand now?
Turnaround to electric
ING research shows that for consumers there are three main barriers that prevent them from choosing an electric car; insufficient charging facilities, a (too) limited range and a (too) high purchase price. However, these barriers are rapidly being overcome:
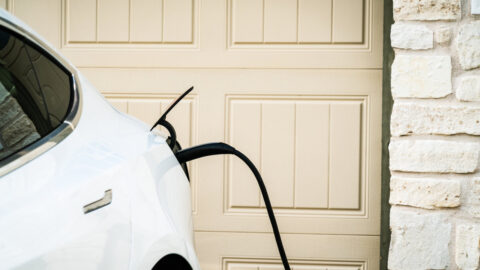
- The network of fast charging points is growing and faster charging options are becoming available. Many new models are already capable of fast charging at around 100 kW or more. Tests are under way for future models with 400 kW fast charging, where you 'top up' 100 kilometres in three minutes.
- The energy density of batteries is getting better and better. Where versions of the Nissan Leaf and BMW i3 of some years back got just over 100 kilometres, the standard for new models now is mostly a range of at least 300 kilometres. In some cases, it even exceeds 500 kilometres.
- The cost of batteries is getting lower. ING research found that by 2024 in the key German market, an electric car in the VW Golf segment with a 60 kWh battery can compete with a comparable petrol car on TCO (total cost of ownership) and excluding subsidies.

Competitive advantage disappears
Besides overcoming the three major barriers, battery electric cars have a number of other strengths. On efficiency, smoothness, silence and acceleration, electric drive wins over fuel engines. This is bad news for European carmakers, who have been leaders in fuel engines for years. They will be much less able to differentiate themselves on powertrains in the future.
Dependence on Asia increases
On top of that, the most important component in the electric powertrain, the battery, is mainly developed and produced in Asia. In 2017, Europe accounted for a 25% share in fuel engines, but only 3% in batteries. China held more than half of the production followed by South Korea, Japan and the US. The largest battery manufacturers are US-Japanese combo Tesla-Panasonic, Korea's LG and from China CATL and BYD.

Europe needs to act
Although the market share of battery electric cars is still small, growth will be huge in the coming years. Tesla has shown over the past year that it can build electric cars in volume. In the US in 2018, it sold about as many units of the Model 3 as added together the BMW 3-series, Audi A4 and Mercedes C-class. Chinese manufacturers are also increasingly making electric cars and have plans to export to Europe. Besides increasing pressure from the market, new European emissions requirements for 2030 encourage sales of all-electric cars. So the European car industry needs to act.
Investment in electric car increases
This is why German car manufacturers are investing over €40 billion in electric driving over the next three years. Large battery supply contracts have been concluded and many new electric models are coming. To get a grip on battery production, they are also investing in raw materials. In addition, Europe is working on new battery technology, such as solid-state batteries with a (theoretically) much higher energy density. Looking at current and planned battery production capacity, Europe's share in battery production rises to 10%.
Opportunities and threats
This European catch-up race will present both opportunities and threats for automotive suppliers. Parties in the fuel engine, gearbox and exhaust chain have been able to benefit from rising sales in recent years. Over the next decade, however, they will have to reckon with a sharply declining market. On the other hand, there are opportunities for suppliers in the electric motor and battery production chain and parties involved in factory and production line conversions.
For more information, see ING's report on the rise of electric cars.
Article: Max Erich, sector economist Industry
Information: Gert Jan Braam, sector banker Industry | Homepage ING-Industry